• Menu
  • Skip to right header navigation
  • Skip to main content
  • Skip to secondary navigation
  • Skip to primary sidebar
  • Skip to footer

Before Header

Philadelphia Wealth & Asset Management Firm

wealth management

  • Why TBA?
    • Why Tower Bridge Advisors?
    • FAQs
  • Who We Serve
    • Individuals & Families
    • Financial Advisors
    • Institutions & Consultants
  • People
    • James M. Meyer, CFA® – Chairman of the Board
    • Nicholas R. Filippo – Principal, Chief Marketing Officer
    • Jeffrey Kachel – Principal, Portfolio Manager, CFO, CTO & CCO
    • Chad M. Imgrund – Sr. Research Analyst
    • Christopher E. Gildea – CEO, Senior Portfolio Manager
    • Daniel P. Rodan – Sr. Portfolio Mgr.
    • Christopher M. Crooks, CFA®, CFP® – Chief Investment Officer, Senior Portfolio Manager
    • Michael J. Adams – Sr. Portfolio Manager
    • Shawn M. Gallagher, CFA® – Sr. Portfolio Mgr.
    • Tom Blair – Qualified Plan Advisor, Portfolio Manager
  • Wealth Management
    • Factors to Consider When Choosing a Wealth Management Firm
  • Process
    • Financial Planning
    • Process – Equities
    • Process – Fixed Income
  • Client Service
  • News
    • Market Commentary
  • Video
    • Economic Updates
  • Contact
    • Become A TBA Advisor
    • Ask a Financial Question
  • We are looking to add advisors to our team. Click here to learn more!
  • We are looking to add advisors to our team. Click here to learn more!
  • Click to Call: 610.260.2200
  • Send A Message
  • Why TBA?
    • Why Tower Bridge Advisors?
    • FAQs
  • Services
    • Individuals & Families
    • Financial Advisors
    • Institutions & Consultants
  • People
    • James M. Meyer, CFA – Chairman of the Board
    • Nicholas R. Filippo – Principal, Chief Marketing Officer
    • Jeffrey Kachel – Principal, Portfolio Manager, CFO, CTO & CCO
    • Chad M. Imgrund – Sr. Research Analyst
    • Christopher E. Gildea – CEO, Senior Portfolio Manager
    • Daniel P. Rodan – Sr. Portfolio Mgr.
    • Christopher M. Crooks, CFA®, CFP® – Chief Investment Officer, Senior Portfolio Manager
    • Michael J. Adams – Senior Portfolio Manager
    • Shawn M. Gallagher, CFA® – Sr. Portfolio Mgr.
    • Tom Blair – Qualified Plan Advisor, Portfolio Manager
  • Wealth Management
  • Our Process
    • Financial Planning
    • Process: Equities
    • Process – Fixed Income
  • Client Service
  • News
    • News & Resources
    • Market Commentary
  • Videos
    • Economic Updates
  • Contact
    • Become a TBA Advisor
    • Ask a Financial Question
wealth management

November 22, 2021 – Record highs in the stock market masked an overall deterioration as slowing growth and rising costs impact more companies. While some of the pressures may be peaking or have already peaked, the clear sailing witnessed last spring is unlikely to return.

//  by Tower Bridge Advisors

Lockdowns in Austria sent the Dow and S&P 500 lower on Friday although the NASDAQ continued to rise. Interest rates remained within a tight range.

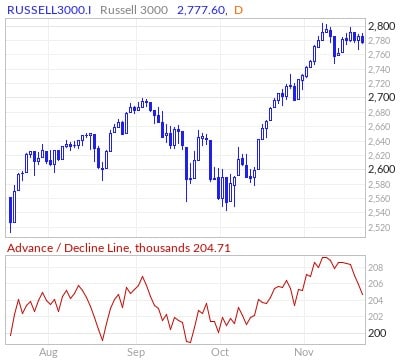
While stocks continue to rise, look at the chart below. It is a chart of the Russell 3000, perhaps the market’s broadest relevant index containing, as the name implies, 3,000 companies. Note that while stocks waver near all-time highs (the blue line on top), the number of shares rising (advances) versus the number of shares declining has been in rather steep decline for several days. What does this mean? It says that a handful of big cap stocks are keeping the leading averages near record levels. But that hides the fact that the overall market has been giving ground for the last few weeks.


What are the implications?

For one, there are increasing and broad concerns.  Covid-19 case numbers are rising yet again, although I would note that the spikes this time are geographically different than they have been.  Do you know any one local market that has been in crisis mode twice?  It seems this disease finds its weak spots, mostly in geographies under-vaccinated and under infected.  I am certainly not an epidemiologist, but a layman’s interpretation is that the disease is running its course.   It isn’t giving up, though, until it runs out of weak spots.  The good news is that hospitalizations, nationally, remain relatively low and life stays normal, at least in the US.  Yet Austria’s experience shows that, worldwide, Covid-19 isn’t ready to disappear quite yet. 

Austria isn’t a world economic power but related nations like Germany matter.  Yet the overall direction relative to Covid-19 is that the worst is over even if isolated hot spots happen for an extended period.  Investors and corporations can deal with that.

Indeed, there are increasing signs that recovery is continuing and that supply chain bottlenecks are being reduced. The only serious retardant to overall GDP growth next year will be a decline in federal government spending as crisis Covid-19 payments wind down.   Most already have.

The markets have other concerns beyond Covid-19.  A major one has been inflation.  Yet long-term interest rates suggest markets are less concerned than the media or whoever responds to consumer surveys.  Of course, we all know that inflation at the moment is close to 6%, but that won’t last.  A lot of that is commodity centric.  Commodity prices are volatile.  When prices rise, supply increases as demand decreases.  Balance gets restored.  Don’t expect the prices for beef, gasoline, or homes to keep rising at their current pace for months or years to come.   The real question is whether wage and rent inflation will persist.  Can fading Covid fears entice millions back into the workforce?  Or have life habits changed enough such that labor participation rates will never recover to pre-Covid levels?

Side by side with this discussion is the future course of monetary policy.  To that end, President Biden’s choice of who will lead the Fed should be announced this week.  Although there do not appear to be significant policy differences regarding interest rates between incumbent Jerome Powell and lead contender Lael Brainard, Mr. Biden has at least two other Fed Board seats to fill.  Markets want the Fed to remain independent of political pressure. Should Mr. Biden nominate three or four who advocate for greater regulation and supervision, markets could react negatively.

Next, while the House has finally passed the Build Back Better bill, it got the votes needed by stuffing the bill with new agenda items that have no chance of staying once the Senate gets its hands on it.  How much chopping and slashing will be required to finish the legislation is still in doubt.  The Senate will ultimately pass something.  Then it will be up to the House to either accept half a loaf or stand on principal and accept none.  The consensus assumption is that the House will pass almost anything to get the bill over the finish line.   Nothing is certain with this fractured Congress.

While all these concerns are important, maybe a glance at Friday’s list of new highs and lows is even more revealing.  Big names like Apple#, Nvidia, Microsoft#, Home Depot#, Alphabet#, and Adobe all set new highs.   In contrast, look at the new low list.  It was filled with yesterday’s hot story stocks, names like Teledoc, Zillow, Robin Hood, Penn National Gaming and Draft Kings, all hot names that now must show that they have any kind of proven economic model that allows them to make sufficient money to justify even their current prices, often 50% or more below their peak over the last 52-weeks. 

It isn’t just the growth imposters that are giving ground.  Oil stocks have been market leaders all year as oil prices surged, but oil prices have started to fade as they normally do in the fall.  Bank stocks were hot for a while as the 10-year Treasury started to rebound, but that has stopped.  Even with good growth numbers, the 10-year yield remains well below spring highs.  The rally in the travel and leisure stocks so savaged by Covid-19 seems to have faded as well.  The stubborn persistence of Covid is one factor.  Maybe a bigger factor is that the market caps of some of the leading cruise ship, airline and hotel stocks had surpassed levels reached in 2019 prior to the pandemic.  Does it make sense for these names to go sharply higher from recent peaks?   Finally, GDP growth peaked in the spring and is on a path to return to normal, meaning 2-4% by the middle or end of next year.   The spending boom of the Federal government that lifted all boats as it handed out Covid relief money right and left has faded.  No more $15 per hour to sit on the couch. 

This shouldn’t be a surprise.  Months ago, we noted that fading growth was inevitable.  It should have been priced in.  To some extent it has. After all, stocks are still near highs, but companies reliant on economic growth, or stocks that depend on euphoric investor mood swings, are fading a bit.  So far, there are few signs that the market is on the precipice of a serious correction.   Some of the hype seems to be fading.   Fading, however, doesn’t mean disappearing.  Record fine art sales in New York last week focused on hot new trends shattering previous price records while old stalwart names attracted buyers but few records.   Sounds a lot like the stock market.  Bitcoin, which surged through the summer and fall is now over 15% below its recent all-time highs.  Mood swings still matter.  I have no idea whether the next $10,000 move in bitcoin is up or down.  Fundamentals don’t matter.

Normally, November and December are good months for stocks.  With the economy still growing, there aren’t a lot of reasons to suspect this year will be different, but equities have come a long way from the Covid-19 nadir.   Should inflation persist at some level higher than the pre-Covid average below 2%, it will provide a headwind.  2020 and 2021 have been rewarding years for investors, but growth rates are fading.  Forward progress from here will be harder.  Markets continue to reward the giant companies that can maintain growth well above average within a decelerating economy.  Those winners are becoming fewer and fewer.  Eventually, they too will be overpriced, and any modest correction cycle will become complete. The naysayers are out there talking up big corrections or a bear market, but that doesn’t seem likely. What does seem likely is a struggle between rising earnings and falling P/E ratios as the economy normalizes.  That suggests a volatile sideways market for a while, not a huge price to pay for the surge experienced over the past two years.

Today, Scarlett Johansson is 37. Mark Ruffalo turns 54.  Jaime Lee Curtis is 63.  Finally, tennis legend Billie Jean King turns 78.   Can you name the rock ‘n roll hit penned in her honor over 40 years ago?

James M. Meyer, CFA 610-260-2220

Tower Bridge Advisors manages over $1.5 Billion for individuals, families and select institutions with $1 Million or more of investable assets. We build portfolios of individual securities customized for each client's specific goals and objectives. Contact Nick Filippo (610-260-2222, nfilippo@towerbridgeadvisors.com) to learn more or to set up a complimentary portfolio review.

# – This security is owned by the author of this report or accounts under his management at Tower Bridge Advisors.

Additional information on companies in this report is available on request. This report is not a complete analysis of every material fact representing company, industry or security mentioned herein. This firm or its officers, stockholders, employees and clients, in the normal course of business, may have or acquire a position including options, if any, in the securities mentioned. This communication shall not be deemed to constitute an offer, or solicitation on our part with respect to the sale or purchase of any securities. The information above has been obtained from sources believed reliable, but is not necessarily complete and is not guaranteed. This report is prepared for general information only. It does not have regard to the specific investment objectives, financial situation or the particular needs of any specific person who may receive this report. Investors should seek financial advice regarding the appropriateness of investing in any securities or investment strategies discussed in this report and should understand that statements regarding future prospects may not be realized. Opinions are subject to change without notice.

Filed Under: Market Commentary

Previous Post: « November 17, 2021- It’s amazing how well corporations have navigated a minefield littered with disease, shortages, and rising inflation. The ability to pivot quickly is the hallmark of good leadership.
Next Post: February 22, 2021 – The biggest factor this morning is the ongoing rise in 10-year bond yields. Higher yields mean lower P/Es for stocks. They impact growth stocks more than value names. As the economy recovers in a rising rate environment, watch for better relative performance from value sectors and a sharp headwind to excessive speculative activity. »

Primary Sidebar

Market Commentary

Sign Me Up!

Latest News

  • September 23, 2026 – With safe bonds paying 5%, ordinary companies are struggling to look attractive—leaving only the booming AI giants able to keep up with the math, even as soaring expectations and heavy spending create new risks of their own.
  • September 16, 2026 – Today is decision day for the Federal Reserve. A small interest rate hike is mostly discounted in expectations, but it may be more of a surprise if we do not get one. Energy prices and global bond yields have been marching higher over the last few weeks. Coupled with concerns surrounding an AI spending slowdown, it is no wonder that stocks have taken it on the chin recently.
  • September 9, 2026 – Back-to-school season finds investors studying a shifting market, a resilient economy, and the next chapter of AI. What does the market’s report card reveal—and why might patience earn the highest marks?
  • September 2, 2026 – New Federal Reserve Chairman Kevin Warsh noted recently that he wants to avoid a “Hall of Mirrors” problem. That is, if markets rely on the Fed’s guidance, and the Fed relies on market prices to adjust policies, then the Fed is more likely to be blinded to new developments. Energy prices and global bond yields are mirroring each other as they move higher, and may force a policy response from the Fed as the year progresses.
  • August 26, 2026 – Washington’s attempt to artificially hold down interest rates can’t hide a $40 trillion debt, and if market reality eventually pushes rates higher, high-risk and speculative investments will suffer the most painful losses.
  • August 19, 2026 – This week we received data on the housing market as well as earnings reports from major home improvement retailers. Higher mortgage rates and higher input costs are impacting buyers, builders, and the construction materials providers along the supply chain, leaving the housing market in a sideways holding pattern. Like Homer’s Odyssey, housing and equity markets have been battling a series of obstacles all year on the path to new highs.
  • August 12, 2026 – Big Tech’s $730 billion annual AI infrastructure sprint faces potential headwinds from severe power grid bottlenecks and lagging software monetization, making disciplined, risk-budgeted portfolio exposure a prudent strategy to capture long-term secular growth while buffering against a possible sharp correction.
  • August 5, 2026 – Stock markets rebounded this week on lower oil prices coming on the heels of a temporary cessation of Middle East tensions. Oil prices dropped about 10% this week, and corporate profits have been coming through stronger than expected. SpaceX reported its first quarter as a public company, and equity markets are once again rocketing to new all-time highs.
  • July 29, 2026 – As overstretched AI valuations fracture against a hawkish Federal Reserve and mounting consumer credit strain, the rotation out of tech into value equities proves that single-sector concentration is risky.
  • July 22, 2026 – The stock market is behaving like a duck swimming feverishly underwater, but on the surface seems to be gliding along. We have seen rapid rotation between sectors as investors try to decipher moves in oil prices, inflation, interest rates and earnings. Major bank earnings came in ahead of expectations this quarter, and the consumer appears to be maintaining strong spending levels. However, technology stocks have risen and fallen like the tides. We will gain more clarity from some of the large AI spenders this week.

Footer

Wealth Management Services

  • Individuals & Families
  • Financial Advisors
  • Institutions & Consultants

Important Links

  • ADV Part 2 & CRS
  • Privacy Policy

Tower Bridge Advisors, a Philadelphia Wealth and Asset Management firm, is registered with the SEC as a Registered Investment Advisor.

Portfolio Review

Is your portfolio constructed to meet your current and future needs? Contact us today to set up a complimentary portfolio review, using our sophisticated portfolio analysis system.

Contact

Copyright © 2026 Tower Bridge Advisors

Philadelphia Wealth & Asset Management, Registered Investment Advisors

300 Barr Harbor Drive
Suite 705
West Conshohocken, PA 19428

Phone: 610.260.2200
Toll Free: 866.959.2200

  • Why Tower Bridge Advisors?
  • Investment Services
  • Our Team
  • Wealth Management
  • Investment Process
  • Client Service
  • News
  • Market Commentary
  • Economic Update Videos
  • Contact