• Menu
  • Skip to right header navigation
  • Skip to main content
  • Skip to secondary navigation
  • Skip to primary sidebar
  • Skip to footer

Before Header

Philadelphia Wealth & Asset Management Firm

wealth management

  • Why TBA?
    • Why Tower Bridge Advisors?
    • FAQs
  • Who We Serve
    • Individuals & Families
    • Financial Advisors
    • Institutions & Consultants
  • People
    • James M. Meyer, CFA® – Chairman of the Board
    • Nicholas R. Filippo – Principal, Chief Marketing Officer
    • Jeffrey Kachel – Principal, Portfolio Manager, CFO, CTO & CCO
    • Chad M. Imgrund – Sr. Research Analyst
    • Christopher E. Gildea – CEO, Senior Portfolio Manager
    • Daniel P. Rodan – Sr. Portfolio Mgr.
    • Christopher M. Crooks, CFA®, CFP® – Chief Investment Officer, Senior Portfolio Manager
    • Michael J. Adams – Sr. Portfolio Manager
    • Shawn M. Gallagher, CFA® – Sr. Portfolio Mgr.
    • Tom Blair – Qualified Plan Advisor, Portfolio Manager
  • Wealth Management
    • Factors to Consider When Choosing a Wealth Management Firm
  • Process
    • Financial Planning
    • Process – Equities
    • Process – Fixed Income
  • Client Service
  • News
    • Market Commentary
  • Video
  • Contact
    • Become A TBA Advisor
    • Ask a Financial Question
  • We are looking to add advisors to our team. Click here to learn more!
  • We are looking to add advisors to our team. Click here to learn more!
  • Click to Call: 610.260.2200
  • Send A Message
  • Why TBA?
    • Why Tower Bridge Advisors?
    • FAQs
  • Services
    • Individuals & Families
    • Financial Advisors
    • Institutions & Consultants
  • People
    • James M. Meyer, CFA – Chairman of the Board
    • Nicholas R. Filippo – Principal, Chief Marketing Officer
    • Jeffrey Kachel – Principal, Portfolio Manager, CFO, CTO & CCO
    • Chad M. Imgrund – Sr. Research Analyst
    • Christopher E. Gildea – CEO, Senior Portfolio Manager
    • Daniel P. Rodan – Sr. Portfolio Mgr.
    • Christopher M. Crooks, CFA®, CFP® – Chief Investment Officer, Senior Portfolio Manager
    • Michael J. Adams – Senior Portfolio Manager
    • Shawn M. Gallagher, CFA® – Sr. Portfolio Mgr.
    • Tom Blair – Qualified Plan Advisor, Portfolio Manager
  • Wealth Management
  • Our Process
    • Financial Planning
    • Process: Equities
    • Process – Fixed Income
  • Client Service
  • News
    • Market Commentary
  • Videos
  • Contact
    • Become a TBA Advisor
    • Ask a Financial Question
wealth management

October 1, 2021 – Concerns, they are aplenty. Markets ended September on a sour note, as major averages tested last week’s spike lows. The key to the next 5% move revolves around equities holding near current support levels. Near-term headwinds are compounding, pointing to more downside risk. Rest assured, this bull market is not over yet.

//  by Tower Bridge Advisors

Another quarter is in the books as we enter October which historically has been a favorable seasonal time to be invested. This is especially true in years where stock market returns are already generous. History says we should expect a solid finish for 2021. Even after a nearly 5% drop across the board in September, the S&P, Dow Jones Industrial Average and Nasdaq are still up 15%, 11% and 12% respectively this year. Although September carried on its long tradition of increased volatility, major averages are within 5% of all-time highs.

Indices closed at support levels yesterday as selling pressure increased into the close. Every S&P sector was down. One might call that indiscriminate selling; get out at any price. Holding here and consolidating during what is likely to be a choppy earnings season is critical. 4,300 on the S&P could be a line in the sand. Closing below that may bring in additional technical sellers. Chart reading has minimal real-world fundamental research applied to it, but market participants and black box trading firms pay strict attention to well-recognized support levels. Once a ball gets rolling downhill, it can accelerate. If this happens, opportunities will arise. It is always good practice to build a shopping list and identify entry points. Odds of this happening now are a coin flip, especially as headwinds mount up.

What could go wrong from here? Let me count the ways:

1. Last mile deliveries during the all-important holiday season have been a consistent issue as internet sales exploded over the past decade. This time around, it is the first mile that has problems. Shipping from partially closed factories to jam-packed ports and on to ships that are stuck in traffic will prove difficult this season. Companies that prepared for this in the summer will benefit. Others are looking at lost sales.
2. A slew of earnings reports will be out, starting in two weeks. If off-quarter reports from Nike#, FedEx#, CarMax# or Accenture# are any indication, it is going to be a rough period. They all reported decent, not great, earnings. Investors have become accustomed to sizable beats on revenue and EPS over the past few quarters. Outperforming analyst expectations at a record pace was never going to continue. We are already well above pre-pandemic levels in many ways, which surprised investors over the past few quarters. Now they expect more. Growth from here will not be a straight line. Look at how far we’re already above 2019 pre-pandemic levels.

3. A major factor contributing to less than stellar earnings reported in September stems from the obvious: freight delays, wage pressures, lack of talented employees and transportation costs. Demand is robust, but margin pressures and a lack of finished goods are not ideal situations with stocks up 15 – 20% already.
4. DC bickering over debt limits, 2 massive spending bills awaiting votes, possible tax increases and declining approval ratings for the current regime also brings pressure. Markets do well when things are calm and belief in the President is high. Consumer confidence has more power than one may think.
5. Massive cash flow is bringing share buybacks to record highs:
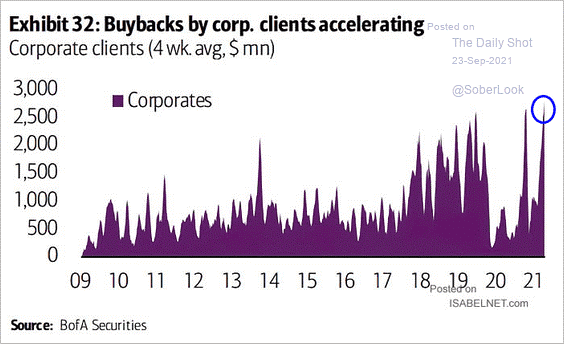
This is great overall, but during reporting season buybacks are paused. This removes a sizable buyer of stocks.
6. China will always be a wild card, but recent events there are still surprising. Their latest move is to order state-owned energy companies to secure oil supplies at all costs. The last thing we need is an energy crunch bringing comparisons back to the 1970’s inflationary cycle. Once this news broke yesterday, stocks went from green to red across the board.
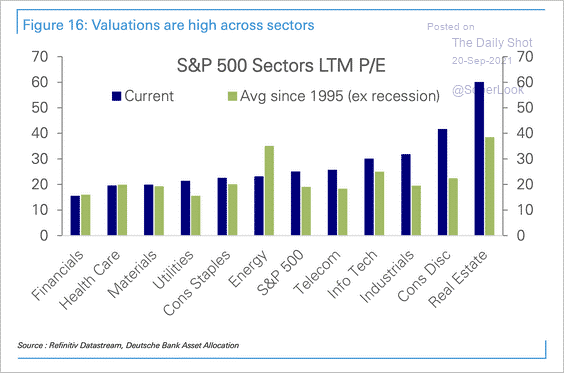
7. Valuations remain elevated, leaving no room for error (on earnings or interest rates):
8. Government stimulus is starting to decline as Central Banks in developed markets are expected to slow bond purchases. More concerning, emerging market central banks have been raising rates all year in order to combat inflation. A tightening cycle is upon us albeit in the infancy stage. This won’t matter much in the near term, but conditions will be less stimulative than the past 18 months.

We’re not ending this quarter on a sour note. 5% – 10% corrections happen, especially after major averages double in price just 18 months. Covid-induced supply chain disruptions will improve from here. Earnings expectations got ahead of themselves in the near-term, but today’s missed revenue opportunities become tomorrow’s prospects. Valuations, although stretched right now, will gradually decline as GDP continues to grow above trend. So long as interest rates remain range bound, markets can support higher than usual P/Es. By the end of October, debt ceiling woes should be resolved. Stimulus bills will hopefully get approved before year-end as well.

We welcome the 4th quarter and recognize that any further declines will probably be an opportunity.

Captain Marvel’s Brie Larson is 32 today while Julie Andrews turns 86. On the political side, former President Jimmy Carter is now 97 and Prime Minister Theresa May is 65.

James Vogt, 610-260-2214


Tower Bridge Advisors manages over $1.5 Billion for individuals, families and select institutions with $1 Million or more of investable assets. We build portfolios of individual securities customized for each client's specific goals and objectives. Contact Nick Filippo (610-260-2222, nfilippo@towerbridgeadvisors.com) to learn more or to set up a complimentary portfolio review.

# – This security is owned by the author of this report or accounts under his management at Tower Bridge Advisors.

Additional information on companies in this report is available on request. This report is not a complete analysis of every material fact representing company, industry or security mentioned herein. This firm or its officers, stockholders, employees and clients, in the normal course of business, may have or acquire a position including options, if any, in the securities mentioned. This communication shall not be deemed to constitute an offer, or solicitation on our part with respect to the sale or purchase of any securities. The information above has been obtained from sources believed reliable, but is not necessarily complete and is not guaranteed. This report is prepared for general information only. It does not have regard to the specific investment objectives, financial situation or the particular needs of any specific person who may receive this report. Investors should seek financial advice regarding the appropriateness of investing in any securities or investment strategies discussed in this report and should understand that statements regarding future prospects may not be realized. Opinions are subject to change without notice.

Filed Under: Market Commentary

Previous Post: « June 18, 2021-Fed announcements usually take a few days before the market figures out what they really said. This time is no different as rates initially spiked but made a 180 degree turn yesterday. Winners and losers in the stock market also flip-flopped. What to do now?
Next Post: October 4, 2021 – A tough September is not a harbinger of what’s to come. The Delta variant is fading, and interest rates are not likely to rise as fast as they did in September. Inflation concerns remain. However, that should mute future upside. Higher earnings, on the other hand, will mute the downside. »

Primary Sidebar

Market Commentary

Sign Me Up!

Latest News

  • October 14, 2026 – The last few years have witnessed a concentrated stock market rally, with this year as no exception. Only about 30% of S&P 500 stocks have performed better than the index over the past 3 years. That means that about 70% of stocks have underperformed the S&P 500. About 45% of stocks in the S&P 500 are actually in negative territory this year. Recent bank earnings reports suggest continued economic growth, although bank stocks have been in correction territory recently also.
  • October 7, 2026 – Rapidly rising Treasury yields are turning the screws on cheap money and over-leveraged debt, making real portfolio diversification the defense before today’s unchecked AI spending boom meets an inevitable profit hangover.
  • September 30, 2026 – Like the rings on a tree cross-section, the economy and markets are reacting to external stimuli and environmental shocks. Corporate earnings and economic growth continue to be solid, although higher interest rates threaten to slow the current expansion. The Fed believes a bit of pruning will continue to be necessary to keep inflation under control.
  • September 23, 2026 – With safe bonds paying 5%, ordinary companies are struggling to look attractive—leaving only the booming AI giants able to keep up with the math, even as soaring expectations and heavy spending create new risks of their own.
  • September 16, 2026 – Today is decision day for the Federal Reserve. A small interest rate hike is mostly discounted in expectations, but it may be more of a surprise if we do not get one. Energy prices and global bond yields have been marching higher over the last few weeks. Coupled with concerns surrounding an AI spending slowdown, it is no wonder that stocks have taken it on the chin recently.
  • Trump Accounts Explained: What Parents Need to Know
  • September 9, 2026 – Back-to-school season finds investors studying a shifting market, a resilient economy, and the next chapter of AI. What does the market’s report card reveal—and why might patience earn the highest marks?
  • September 2, 2026 – New Federal Reserve Chairman Kevin Warsh noted recently that he wants to avoid a “Hall of Mirrors” problem. That is, if markets rely on the Fed’s guidance, and the Fed relies on market prices to adjust policies, then the Fed is more likely to be blinded to new developments. Energy prices and global bond yields are mirroring each other as they move higher, and may force a policy response from the Fed as the year progresses.
  • A Personalized Approach to Wealth Management
  • August 26, 2026 – Washington’s attempt to artificially hold down interest rates can’t hide a $40 trillion debt, and if market reality eventually pushes rates higher, high-risk and speculative investments will suffer the most painful losses.

Footer

Wealth Management Services

  • Individuals & Families
  • Financial Advisors
  • Institutions & Consultants

Important Links

  • ADV Part 2 & CRS
  • Privacy Policy

Tower Bridge Advisors, a Philadelphia Wealth and Asset Management firm, is registered with the SEC as a Registered Investment Advisor.

Portfolio Review

Is your portfolio constructed to meet your current and future needs? Contact us today to set up a complimentary portfolio review, using our sophisticated portfolio analysis system.

Contact

Copyright © 2026 Tower Bridge Advisors

Philadelphia Wealth & Asset Management, Registered Investment Advisors

300 Barr Harbor Drive
Suite 705
West Conshohocken, PA 19428

Phone: 610.260.2200
Toll Free: 866.959.2200

  • Why Tower Bridge Advisors?
  • Investment Services
  • Our Team
  • Wealth Management
  • Investment Process
  • Client Service
  • News
  • Market Commentary
  • Contact